
Welcome to Global Data Center Hub. Join investors, operators, and innovators reading to stay ahead of the latest trends in the data center sector in developed and emerging markets globally.
In this week’s issue:
First, the buildout is shifting down in size. Crusoe closed a $3.9 billion Series F at a $30.9 billion valuation. The same week, CNBC reported Anthropic and OpenAI are hunting deals of 20 to 30 megawatts. When the biggest buyers of compute shop small, which end of the market reprices first?
Then, the Middle East and Africa carry both sides of the risk ledger. AWS says it cannot restore its Bahrain region and one UAE cloud zone damaged in the Iran conflict. Digital Parks Africa announced a Tier IV build in Lagos, and South African groups pushed back on hyperscale growth.
Finally, capital keeps crossing borders. The UAE pledged $46 billion to Germany with data centers a key focus. Anthropic signed a reported $32 billion lease at Zerra DC’s Queensland campus.
Let us get into it.
The $3.9 billion raise and the 20-megawatt signal
The small end reprices first. Crusoe closed a $3.9 billion Series F on Wednesday at a $30.9 billion valuation. Atreides Management, Mubadala Capital, and Valor Equity Partners led the round. NVIDIA, GIC, and the Qatar Investment Authority joined it.
The same week, CNBC reported that Anthropic and OpenAI are seeking data center deals of 20 to 30 megawatts. The sources are anonymous. The reported reason is speed. An existing shell delivers capacity in months, and a gigawatt campus delivers it in years.
Read the two facts together. Crusoe’s release commits the new capital to campuses and to modular Crusoe Spark units at once. The buyer side and the builder side converged on the same answer this week. Speed to usable capacity now beats scale.
So, before you underwrite the next gigawatt campus, price the tenant’s alternative. A lab that can lease 25 megawatts next quarter will not pay a premium to wait four years for your build.
The structure behind the $3.9 billion, and the two other moves that ran the same playbook this week, are in The Mechanism below.
Sponsored By: Global Data Center Hub
Your trusted source for global AI infrastructure analysis. Every week, we break down the trends shaping the future of data centers, cloud, and AI, from emerging markets to hyperscale battlegrounds.
📰 Subscribe to get expert insights delivered to your inbox.
THIS WEEK BY REGION
The week’s biggest moves — what happened and what it signals.
North America
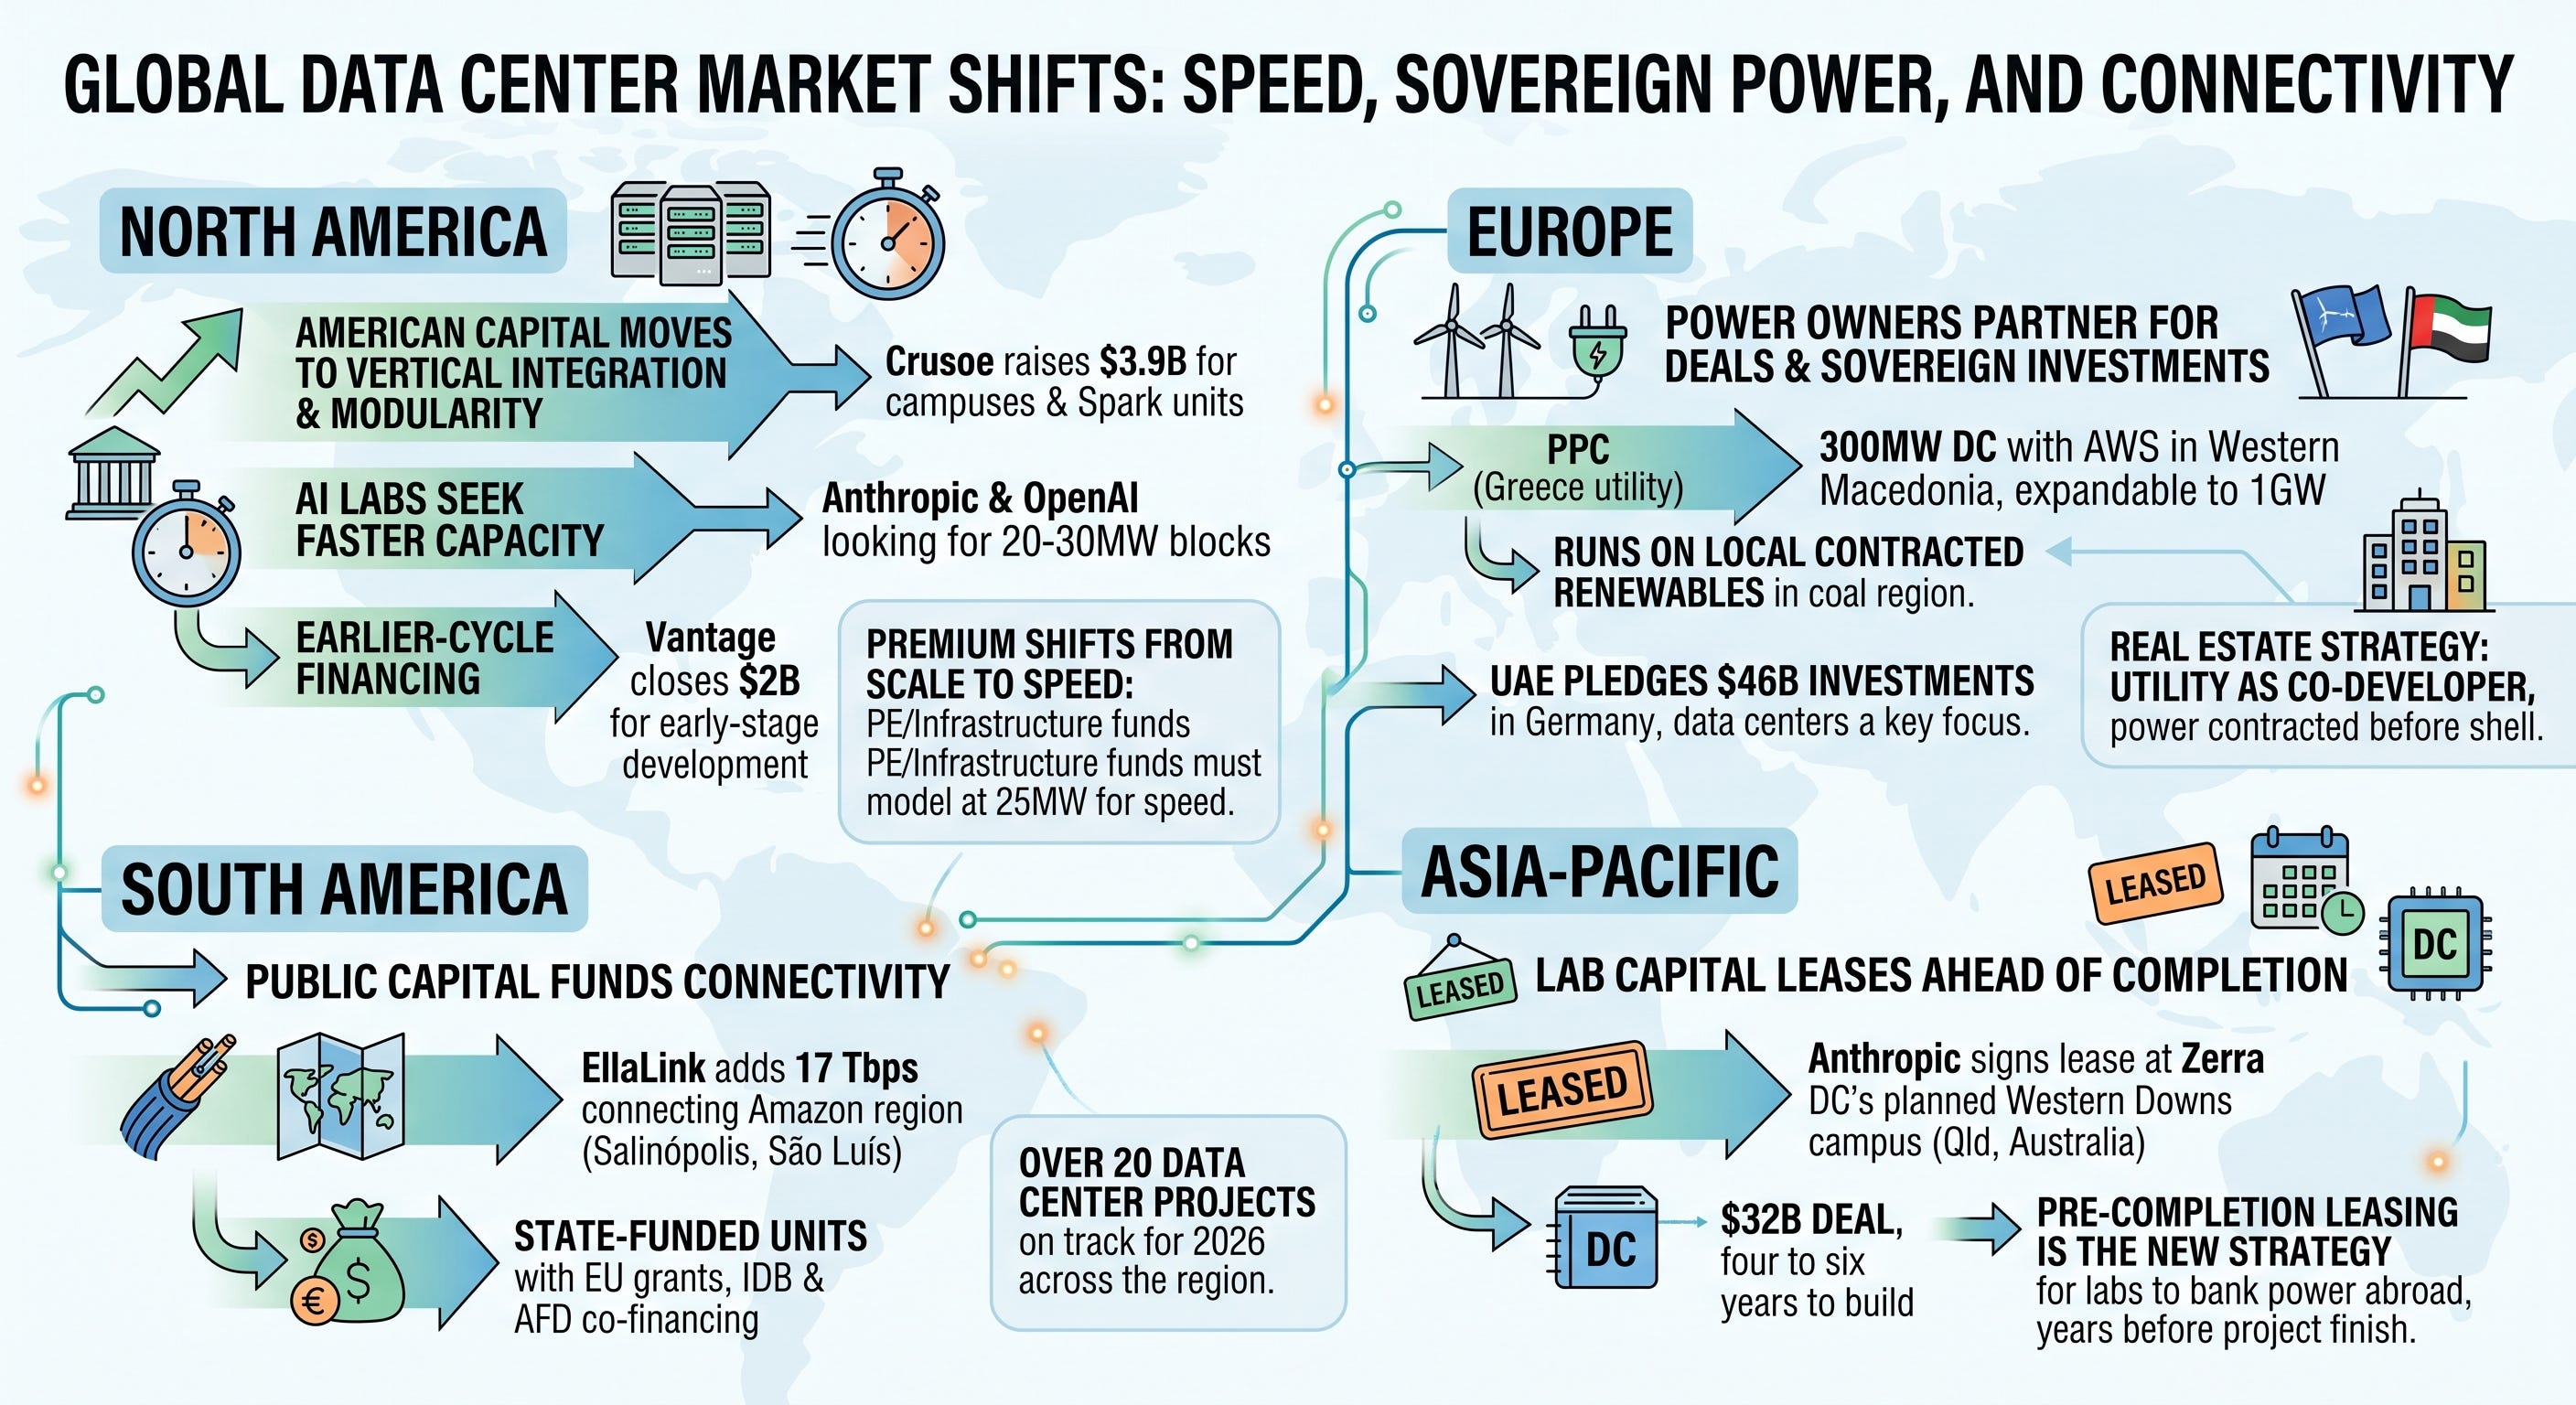
American capital moved across the size spectrum this week. Crusoe raised $3.9 billion for vertically integrated campuses and modular Spark units, while Anthropic and OpenAI reportedly seek 20–30MW blocks to add capacity faster.
Credit moved earlier in the cycle too. Vantage closed $2 billion of committed development financing for early-stage North American projects.
If you run a PE or infrastructure fund, re-run your pipeline math at 25 megawatts. The premium you modeled for scale may now sit with speed.
Europe
Europe’s power owners moved to the deal flow. Greece’s PPC signed a binding agreement with AWS for a 300MW data center in Western Macedonia, expandable to 1GW, with roughly €1 billion each. The site will run on local contracted renewables in a coal region Bloomberg report is welcoming the build.
Sovereign capital moved in parallel. The UAE pledged $46 billion for investment in Germany, with data centers a key focus, while EXA Infrastructure ordered its ninth transatlantic cable, offering 24 fiber pairs and over 500 Tbps by 2029.
Real estate investors, copy the Greek read: the utility is the co-developer, and the power arrives contracted before the shell.
Asia-Pacific
Lab capital reached Australia. Anthropic signed a lease at Zerra DC’s planned Western Downs campus near Dalby, Queensland, reported at $32 billion.
The deal needs Foreign Investment Review Board and council approval, and the campus takes four to six years to build.
Note what the tenant did if you operate in the region: it leased part of someone else’s build years before completion. Pre-completion leasing is now how labs bank power abroad.
South America
South America’s story this week is public capital funding connectivity. EllaLink added 17 Tbps of capacity to the Amazon region, connecting Salinópolis in Pará and São Luís in Maranhão.
State governments funded the units, with EU grants and IDB and AFD co-financing. BNamericas counts more than 20 data center projects across the region on track for 2026.
If you sit at a development finance institution, the sequencing is the lesson: fiber and power land first, and compute follows the concession pipeline.
Below this line, every Sunday: The Mechanism, the structure behind the week’s anchor and where else it ran this week. Then Notable Transactions, two to four structures from the week’s deal tape, broken down.
THE MECHANISM
The structure behind the $3.9 billion, and the two moves that ran it again
Crusoe’s round is all equity. No debt appears in the release. The company raised $3.9 billion against a stated $140 billion of contracted value and more than 6 gigawatts of gross contracted capacity. One gigawatt operates today.
The structure to watch is Spark. Crusoe Spark is a modular unit the company deploys without waiting on a campus. The release commits Series F capital to both formats in one pool. That is a builder pricing speed as a product.
Vantage ran the same logic through credit. Its $2 billion revolving facility funds development-stage assets before stabilization. Committed five-year money moved earlier in the build cycle. That is the credit market’s version of buying speed.
The three differ where your underwriting bites. Crusoe carries speed on equity risk capital. Vantage borrows against it with a collateral pool. The labs, reportedly, simply lease it and skip construction risk entirely.
NOTABLE TRANSACTIONS
Key structures and capital moves from this week’s deal tape.
Generac: Amazon generator supply agreement worth up to $8 billion
Amazon committed $2.4 billion in 2027–2028 purchases under an agreement worth up to $8 billion, plus volume-based warrants. Hyperscalers now offer equity upside to secure scarce manufacturing capacity years in advance.
If you supply the buildout, the mechanism is volume-vested warrants: your biggest customer becomes a shareholder, and your capacity roadmap becomes their hedge.
Vantage Data Centers: $2 billion development-stage revolving credit facility
The five-year revolver, arranged by Evercore and Wells Fargo Securities, is backed by three development assets, with capacity to add more. Insurance capital now shares pre-stabilization development risk once held solely by construction banks.
If you lend into this market, watch the collateral provision: a revolver that adds development assets over time is a platform bet, and you are pricing the sponsor.
If you are new to Global Data Center Hub, visit our Start Here page for more information about the newsletter.
If you found this newsletter useful, share it with a colleague.
Have a great week.
— Obinna
Elemental’s NXS Powered Neural Campus (NA Northgate & Trinity ) & Trillion Token Factory. Compute Based Infrastructure (CBi) 12 X’s Median Density https://lnkd.in/p/dTX7Yte4