
Welcome to Global Data Center Hub. Join investors, operators, and innovators reading to stay ahead of the latest trends in the data center sector in developed and emerging markets globally.
Each month, I track the data center transactions shaping AI infrastructure across North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa. September produced 122 verified deals. Ten patterns stand out.
1. Anthropic was the month’s largest buyer of compute, on three continents.
Akamai signed seven-year project plans committing Anthropic to about $11.6 billion in payments. In Australia, Anthropic signed a long-term lease at Zerra DC’s Western Downs Digital Park, subject to foreign investment review, and in Texas it anchors the month’s top deal.
2. The longest commitments now run a decade or more.
Google signed a 22-year nuclear power purchase agreement with Fortum for the Loviisa plant in Finland. Blockfusion signed a 15-year anchor lease with CoreWeave at Niagara Falls, and Bitdeer AI a ten-year agreement for 65.1MW in Malaysia.
3. Gas is becoming the AI campus’s private power plant.
Aligned broke ground on its 2GW Project Phoenix in Pennsylvania with onsite gas power planned. INNIO booked a firm 450MW order for gas-engine prime power, and Woodway signed for a 22-mile pipeline feeding behind-the-meter generation at an undisclosed hyperscale site.
4. Debt came in four shapes.
VIRTUS closed £2.45 billion of bank debt from 13 lenders. Vantage closed a $2 billion revolving credit facility, NEXTDC priced A$1.1 billion of convertible notes, and ASP Data Center raised NOK 1.6 billion in Norwegian bonds.
5. Nscale played three roles in one month.
It became preferred compute provider to Figure, the physical AI developer, under an initial $3.5 billion commitment in Barstow, Texas. It filed for a New York Stock Exchange listing, and it closed a $2.36 billion first tranche of a $3.36 billion convertible facility, with $1 billion committed by NVIDIA.
6. Equity investors paid up for AI platforms.
Mistral closed a €3 billion Series D at a valuation above €21 billion, and Crusoe raised $3 billion at a $30 billion valuation.
7. Governments rewrote the rules while deals were being signed.
Scotland now requires a full environmental impact assessment for new data centers above 50MW. Virginia restricted nondisclosure agreements with state agencies, California signed seven data center bills on electricity, water and land use, and Thailand paused sector development across 166 projects while it drafts national standards.
8. One conference week produced a cluster of Saudi commitments.
During LEAP 2026, MIS announced a $1.2 billion expansion to 192MW, and NHC Innovation set out an $880 million Khuzam Digital Valley program anchored by BytePlus and NAVER Innovation. AWS and HUMAIN committed up to 50MW at Saudi Arabia’s first AI Zone by 2028.
9. Big buyers are entering Asia through existing buildings and partners.
Amazon signed conditional agreements to buy two Grand Ming data center towers in Hong Kong for at least $278 million. OpenAI became an anchor customer at two Firmus sites in Malaysia, and Microsoft Taiwan is preparing to double its data centers to four.
10. The Nordics drew the largest corporate pledge and a completed platform sale.
Google committed at least €13 billion to Finnish digital infrastructure across four locations for 2027 and 2028. CPP Investments, Equinix and Partners Group completed their acquisition of atNorth at a $4.0 billion enterprise value, alongside a separate $4.1 billion financing package.
The Top 10 Deals Globally
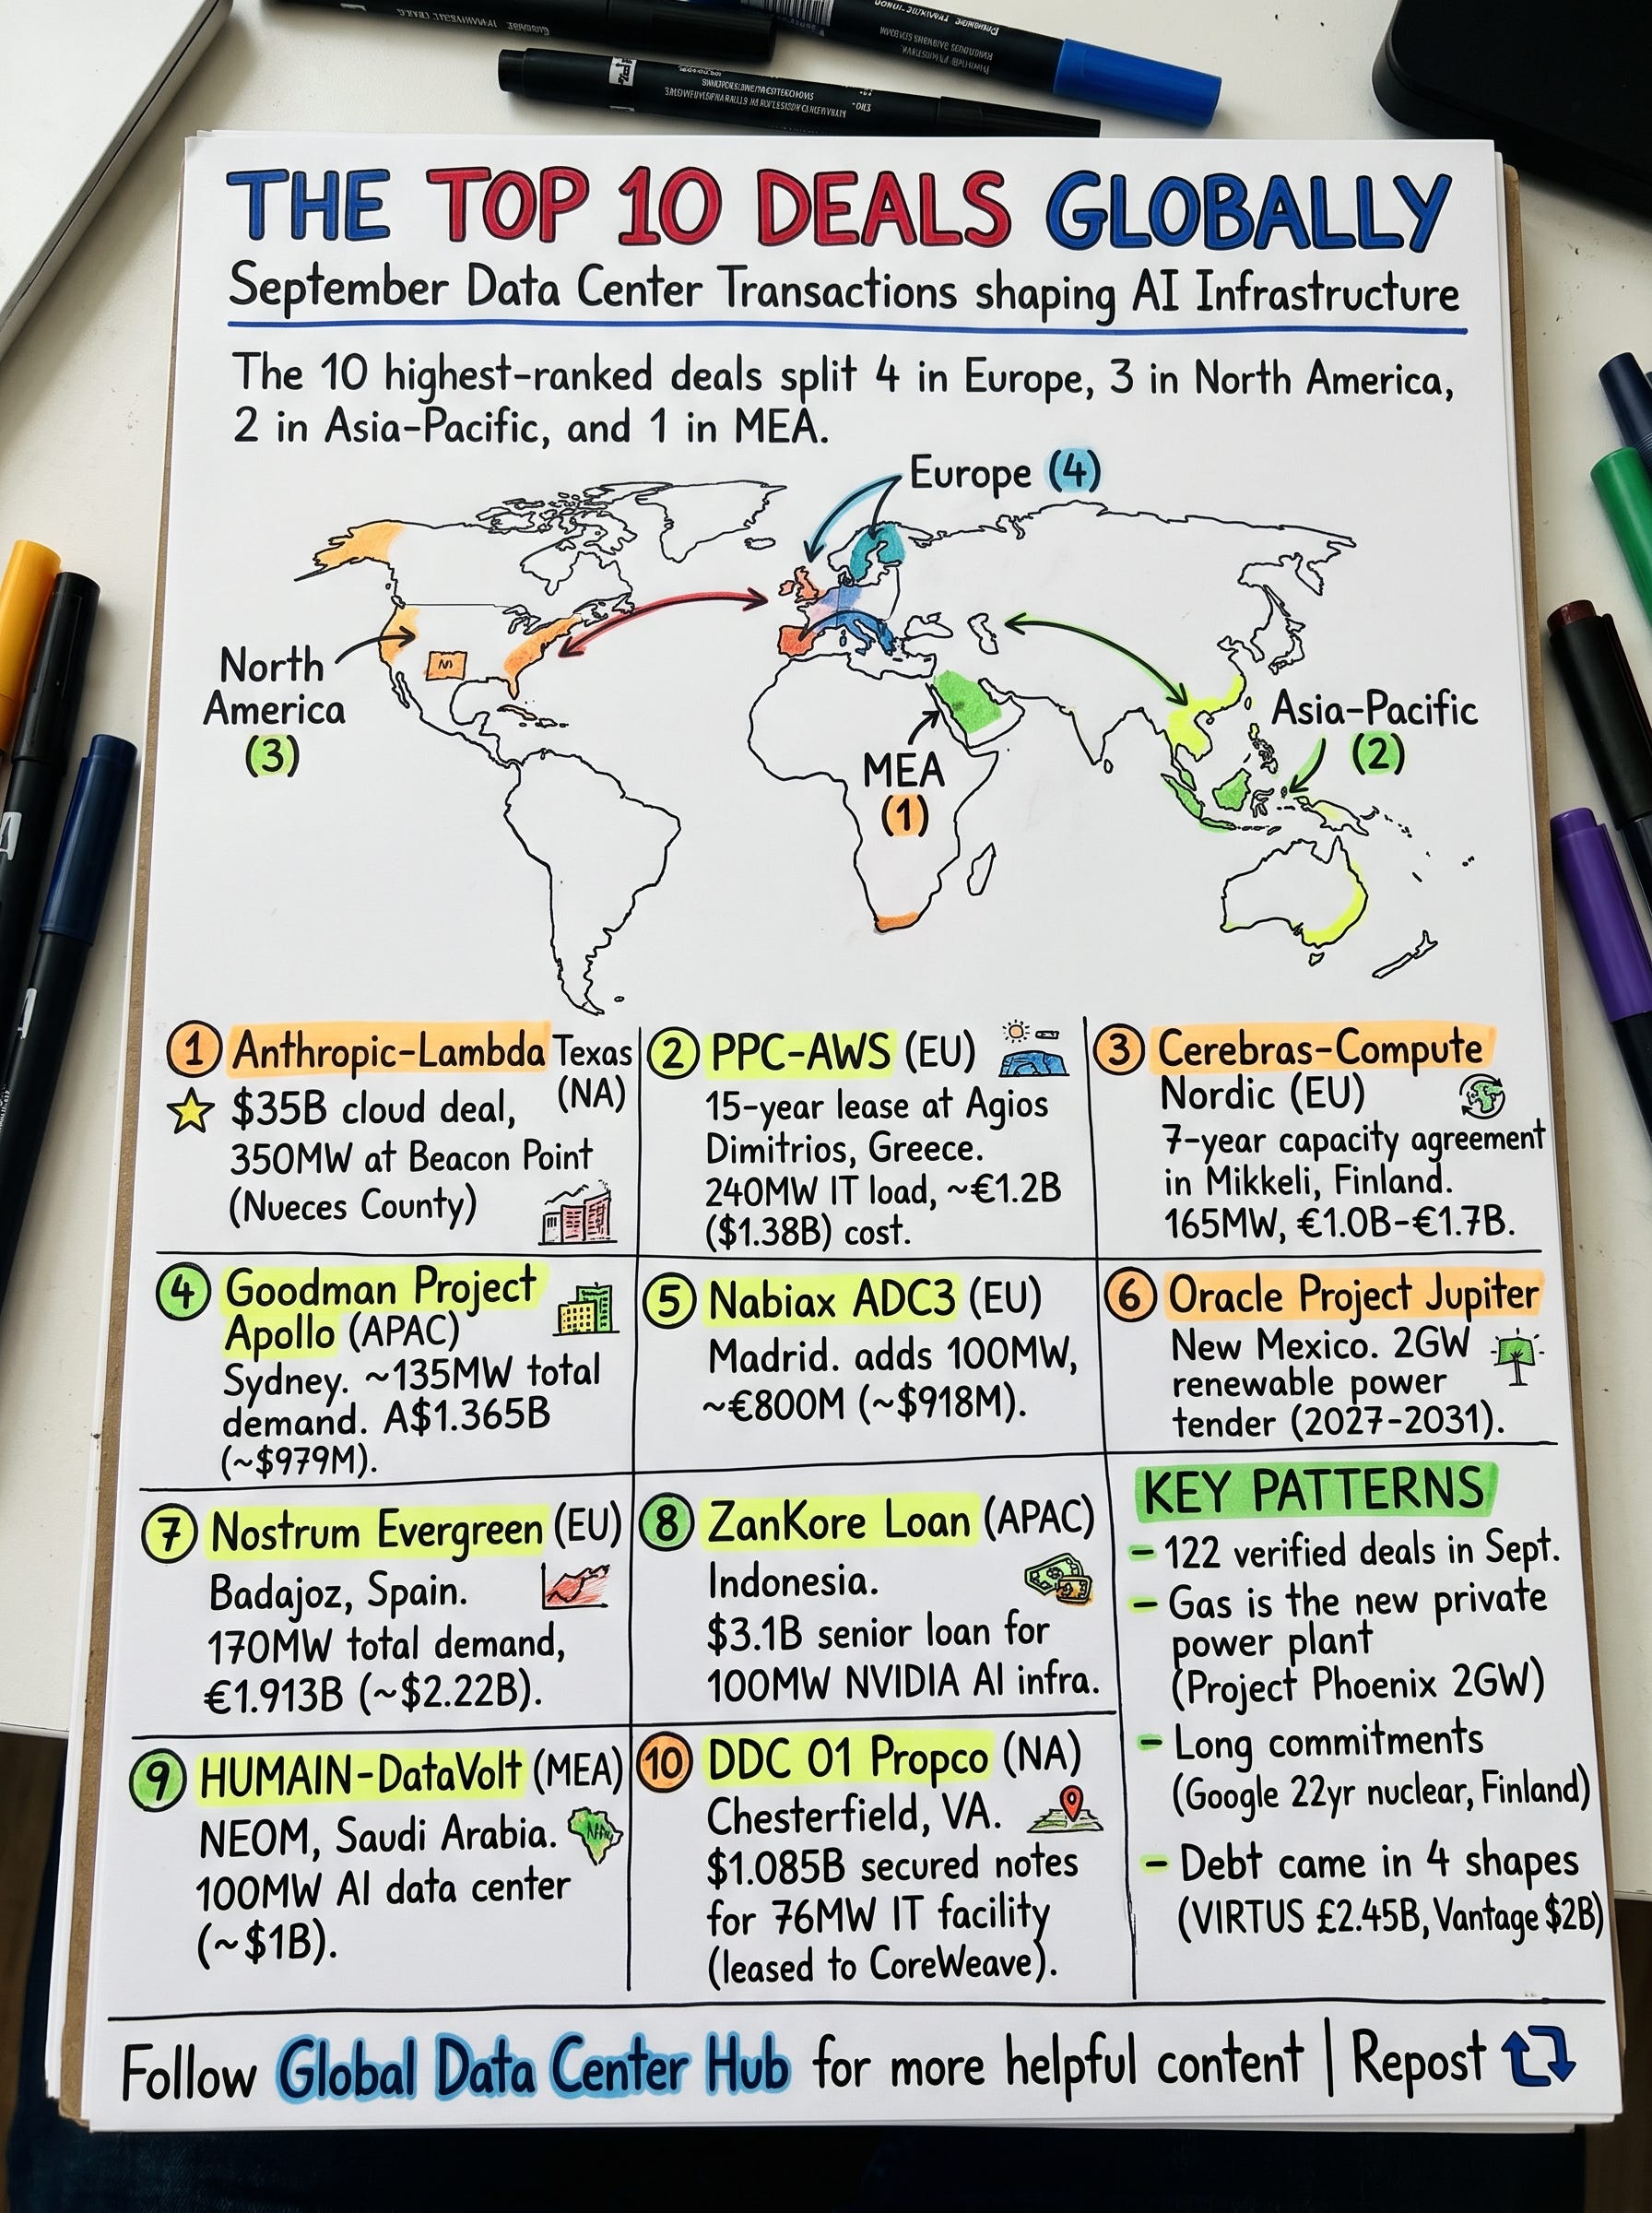
The ten highest-ranked deals split four in Europe, three in North America, two in Asia-Pacific and one in the Middle East and Africa. Latin America’s September activity sat earlier in the build sequence, in a new tax-incentive law, land reservations and grid applications, covered in the regional companion piece.
1. Anthropic–Lambda Texas AI Cloud Agreement (North America)
Anthropic, the AI lab behind Claude, agreed a $35 billion cloud computing deal with Lambda, the AI cloud provider, for roughly 350MW of capacity at Hut 8’s Beacon Point campus in Nueces County, Texas. NVIDIA, the chipmaker whose processors power most AI training, holds the underlying lease, and Lambda supplies the compute.
The $35 billion is contract value, which is revenue, not construction cost. The 350MW sits on capacity already leased at Beacon Point, so it counts once in any total. The largest AI labs now buy compute through layers of landlord, chip supplier and cloud provider.
2. PPC–AWS Agios Dimitrios Data Center (Europe)
PPC, Greece’s largest power utility, signed a binding memorandum with Amazon Web Services, Amazon’s cloud business, for a data center at Agios Dimitrios in Western Macedonia. AWS will lease the finished facility for 15 years. PPC provides the land, buildings and energy infrastructure, and AWS installs and runs the IT equipment.
The first phase is planned at 240MW of IT load within 300MW of total power demand, at an estimated cost of about €1.2 billion ($1.38 billion). A power company now earns 15 years of rent on the electricity and the building together.
3. Cerebras–Compute Nordic Mikkeli AI Capacity (Europe)
Cerebras Systems, the AI chipmaker, signed a seven-year capacity agreement with Compute Nordic Finland for 165MW of contracted IT capacity in Mikkeli. Construction is under way on the first 50MW, built for high-density Cerebras compute.
An analysis by Ramboll cited by Cerebras puts the full build at €1.0 billion to €1.7 billion; the lower figure, about $1.16 billion, is the disclosed lower bound. The deal shows a chipmaker locking in purpose-built capacity for its own hardware.
4. Goodman Project Apollo, Macquarie Park (Asia-Pacific)
Goodman, the Australian industrial property group, received New South Wales planning approval for Project Apollo in Macquarie Park, Sydney. The development has about 135MW of total power demand and 185MW of diesel backup generation, with a development cost of A$1.365 billion (about $979 million). The site will run on grid power. No tenant has been named, and IT load is not disclosed.
5. Nabiax ADC3 Alcalá (Europe)
Nabiax, which operates the Alcalá de Henares data center campus near Madrid, broke ground on ADC3. The project adds about 100MW of planned IT capacity at an estimated €800 million (about $918 million), which is project cost, not closed financing. Scaling through 2029, ADC3 adds more than four times the campus’s existing 22.3MW of IT load.
6. Oracle Project Jupiter Renewable Power Tender (North America)
Oracle, the database and cloud computing company, issued a request for proposals for 2GW of new renewable generation in New Mexico to support its Project Jupiter AI infrastructure. Delivery is targeted for 2027-2031. No contracts have been awarded, and no value is disclosed. The tender is separate from the project’s earlier onsite fuel-cell design, and the two figures are not combined. Oracle is lining up clean power at gigawatt scale before it's needed.
7. Nostrum Evergreen Badajoz Power Authorization (Europe)
The Extremadura regional government granted a preliminary authorization for the electrical infrastructure of Data Riocaya’s Nostrum Evergreen AI campus at the Badajoz logistics platform in western Spain. Environmental filings show a total power demand of 170MW, including 110MW of critical load, and an estimated investment of €1.913 billion (about $2.22 billion). Full campus approval is still to come. A separate 300MW figure is grid connection capacity, not IT load. Securing the grid link first makes the rest of the campus possible.
8. ZanKore $3.1 Billion Term Loan (Asia-Pacific)
ZanKore, a Southeast Asian AI cloud platform, signed a senior term loan of up to $3.1 billion with regional and international lenders. The loan funds an initial 100MW of NVIDIA AI infrastructure in Indonesia. ZanKore’s longer-term target is 1GW. It is one of the month’s largest debt packages, and it shows banks willing to lend billions against AI compute in an emerging market.
9. HUMAIN–DataVolt Oxagon AI Data Center (Middle East and Africa)
HUMAIN and DataVolt, two Saudi AI infrastructure companies, broke ground on a 100MW AI data center at Oxagon in NEOM, the first development inside a planned 360MW first phase of DataVolt’s 1.5GW Red Sea campus. DataVolt’s chief executive put the cost at around $1 billion. Sources do not say whether the 100MW is IT load or total power, and financing was nearly secured, with no amount disclosed. The facility is designed to run on renewable energy and export computing capacity abroad.
10. DDC 01 Propco CoreWeave-Linked Secured Notes (North America)
DDC 01 Propco, backed by a Blue Owl, Cedarwood and PowerHouse joint venture, priced about $1.085 billion of senior secured notes for the Digital Drive data center in Chesterfield County, Virginia. The 76MW IT facility already has a 15-year lease with CoreWeave, the AI cloud provider. The notes are priced at 98.5% of face value with an 8.875% coupon, a yield of about 9.25%. The deal shows a long lease with an AI cloud tenant financed directly in the bond market.
September reads as two markets running on different fuel.
In developed markets, the fuel was financial engineering. DDC 01 Propco turned a CoreWeave lease into secured notes, VIRTUS pulled 13 banks into one package, and Nscale used convertible notes that become shares when it lists.
In emerging markets, the state did the heavy lifting. Brazil enacted REDATA, a nationwide tax-incentive law for data centers. Vodafone Business and a partner agreed to develop Egypt’s first sovereign AI data center, and Saudi Arabia’s HUMAIN put its name on both a NEOM construction site and an AWS capacity target.
Indonesia breaks the pattern and leads rather than waits. ZanKore secured $3.1 billion from regional and international lenders, and BDx is building the first 120MW building of its CGK4 campus in West Java, with the first phase due in early 2027. Private builders are moving on private money.
The split may not hold. The UAE’s €40 billion state-backed program for Germany, which includes data centers, sends state money into a developed market, while Indonesian AI compute draws commercial bank lending. If state capital keeps flowing into developed markets and private debt into emerging ones, which model will build the next gigawatt faster?
The distinction between the different types of commitments is so important. There's an enormous difference between a developer securing a grid connection, signing an anchor tenant and actually closing the financing needed to build. I think tracking how projects move between those stages will tell us much more about the market than headline capacity figures alone.
Anthropic's S-1 puts a total on that September wave. It says that after June 30 the company entered into new agreements and amended existing ones with about $245B of aggregate future minimum payments, on top of $321.4B of leases not yet commenced at June 30 (up from $50.2B at Dec. 31, commencing 2026 to 2028). September deals like Akamai's fall in that post-June window, and the S-1 gives only the totals, which is why per-deal tracking like yours matters.
I work at Equibles and we matched the S-1's compute agreements to the partners' own filings here: https://equibles.com/research/anthropics-s-1-checked-against-amazon-google-microsoft-and-broadcom-filings